
House costs simply went unfavourable, ending an (nearly) 13-year streak of year-over-year value will increase. Sellers are out of choices, patrons are leaving the market, and the Fed is eyeing one other spherical of charge hikes, with sticky inflation ruining the possibilities of actual property value appreciation.
Is that this dangerous information? In the event you’re a vendor, it’s arduous to argue it isn’t. In the event you’re a purchaser, your window of alternative for getting nice offers at a reduced value simply widened. However with dwelling costs flipping unfavourable and sellers caught in a troublesome place, are we truly sliding towards a housing market crash as an alternative of constant the lengthy, gradual, painful correction we’ve been witnessing?
On this November housing market replace, we’re giving the actual possibilities of an actual property crash forming, sharing what has to occur for mortgage charges to reverse and begin heading again right down to the 6% charge vary, and why patrons have simple management over dwelling sellers, with proof that your subsequent rental higher be purchased for lower than listing value. We’ve been saying it for months—costs are getting too good to go on. Are you taking benefit?
Dave:
Housing costs are falling. For the primary time in three and a half years, the median American dwelling value is decrease than it was a yr in the past. It’s not a crash, however it’s a dip. And we didn’t get this sort of dip even with earlier 7% mortgage charges, a five-year inflation spike, and everybody on YouTube saying the bubble is about to pop for the previous few years. So we have to concentrate. And this drop is occurring on the actual second inflation is heating again up. The Fed is mountain climbing once more, and the variety of householders who’re underwater simply hit its highest stage since 2018. So what is that this? Is it the start of one thing dangerous? Is that this the crash so many individuals have referred to as for? Or is it one thing else solely? Immediately on the November housing market replace, we’re going to determine which one it’s and what it is best to truly do about it.
Hey everybody. Welcome to the BiggerPockets Podcast. I’m Dave Meyer, chief funding officer at BiggerPockets. That is our month-to-month housing market replace. Final month, I informed you the availability surge was right here, and now we have now October knowledge and the opposite shoe is beginning to drop. Costs which has been stubbornly holding up whilst stock piled up lastly blinked. The large headline for right this moment is that costs flip unfavourable for the primary time since 2023, and even that temporary interval in 2023 was sort of only a blip as charges went up. I feel this might truly be the start of the primary sustained value drops in US housing since 2012. So in fact we acquired to speak about that right this moment, however there’s a lot else to cowl as effectively. Right here’s what we’re going to get into in right this moment’s episode. First, in fact, we’ll discuss concerning the market.
We’ll speak about costs, gross sales, stock, and the place issues are literally shifting regionally utilizing model new October knowledge. And there’s loads right here this month, loads to think about and to debate. Subsequent, we’ll speak about inflation and what this implies for the Fed. In the event you have been paying consideration, you noticed that we acquired a sizzling CPI print for October. Fed is unquestionably in a mountain climbing cycle for the primary time in three years. And I wish to clarify what that does and extra importantly, what it doesn’t do to your mortgage charge and the market. And third, we’ll get to our month-to-month danger report as a result of we speak about this each single month. We simply acquired new numbers within the November mortgage monitor from ICE, and there’s one quantity in there I actually assume each investor must see. And naturally, alongside the best way, we’ll be decoding what this implies for actual property traders and wish you all to concentrate to this one as a result of these items actually does matter.
Markets just like the one the place we’re in are dangerous, they’ve alternative, however they’re additionally sort of the place the subsequent 5 years of returns truly get made. It’s not throughout growth occasions the place you take advantage of cash. It’s in these awkward, bizarre transitions just like the one which we’re in proper now. And if you happen to perceive what’s shifting proper now, you get to purchase in your phrases as an alternative of the markets and get nice returns that would maintain you for years and even many years to come back. In order that’s the plan. However earlier than we leap in, simply wish to give a fast due to our sponsors, PSF Community. PSF Community is a fractional actual property platform that permits customers to purchase and spend money on actual property by the sq. foot fairly than having to buy entire properties or shopping for arbitrary shares. To study extra, go to psfnetwork.com. All proper, let’s leap into our market recap.
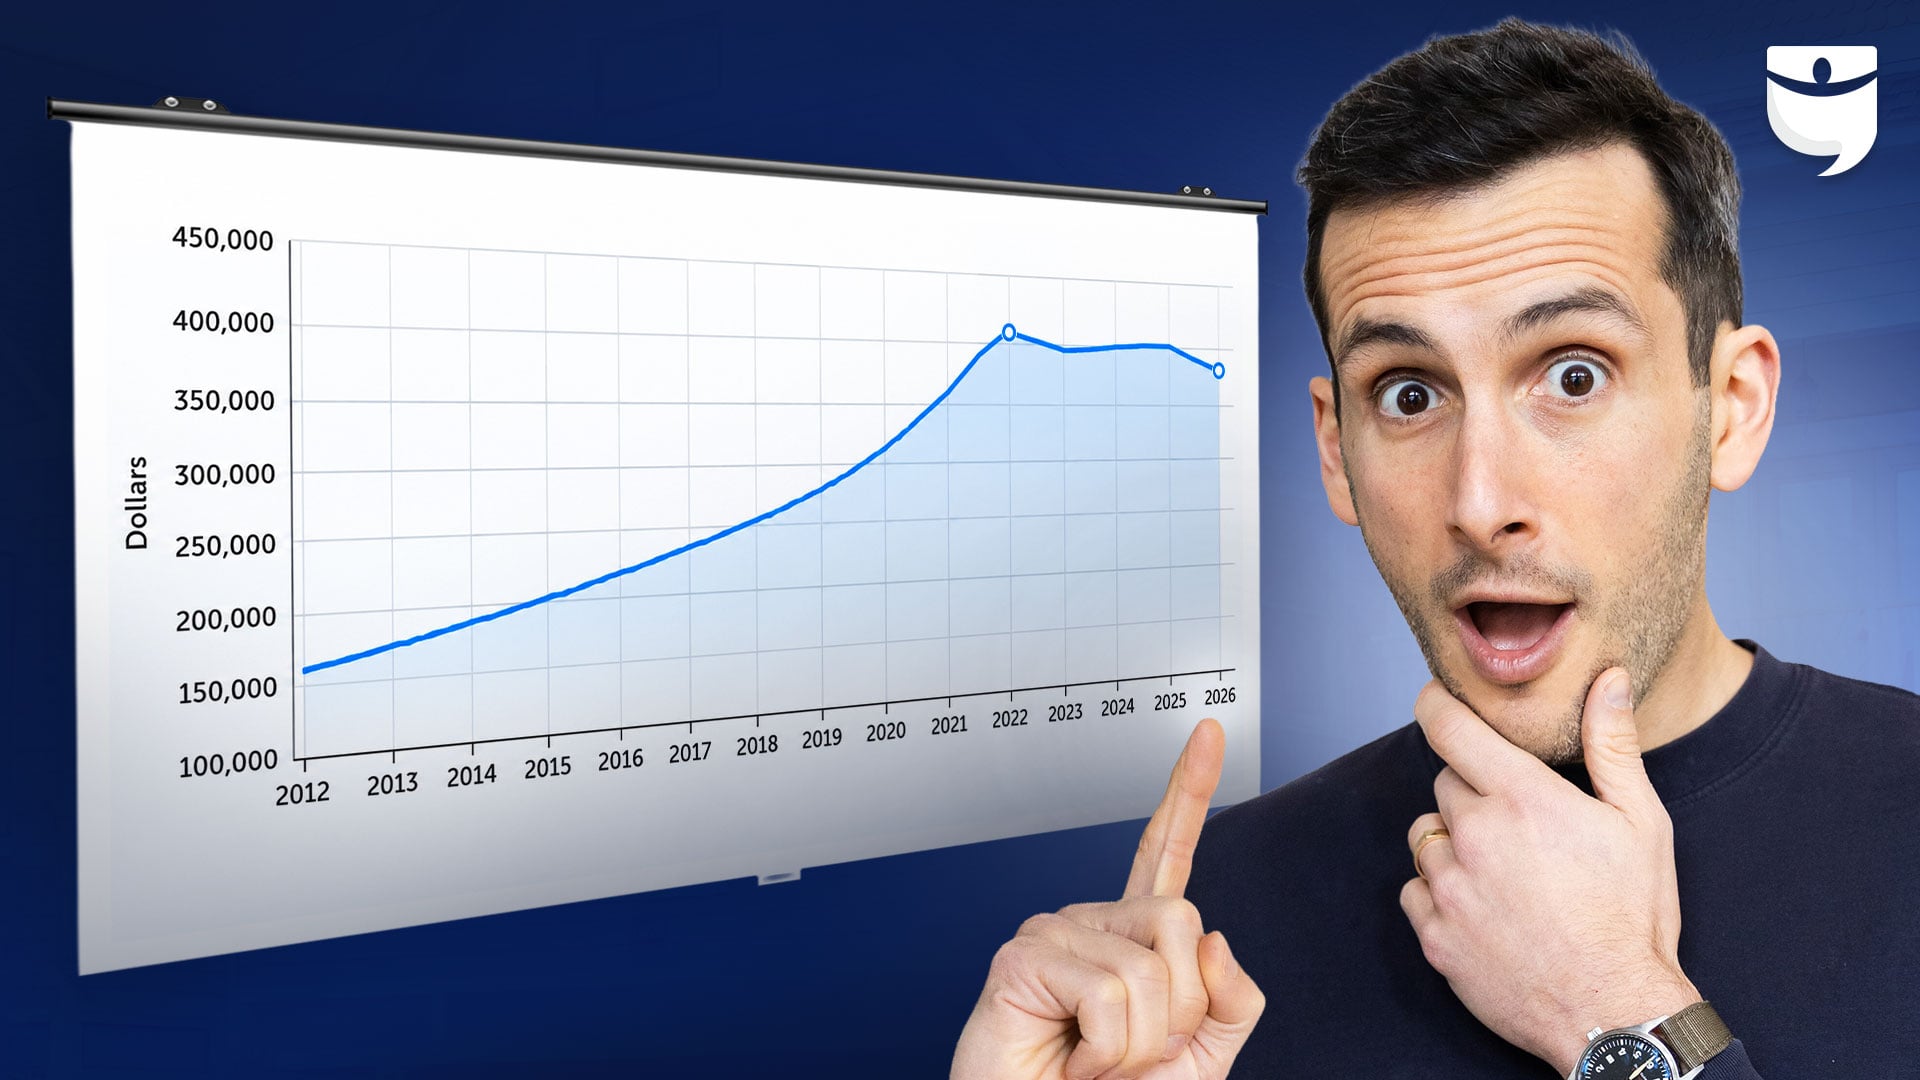
Large headline right here is the streak is over. In accordance with Redfin, the median US sale value in October was $388,600, which is down 0.4% yr over yr. And simply as a reminder, within the housing market, yr over yr is what we care about. Issues occur month to month on a regular basis. That’s often due to what is named seasonality. Costs go up within the spring and summer time months, then they arrive down within the fall and winter months. That’s regular. However after we examine October from 2025 to 2026 and see a decline, that’s notable and is a really massive distinction from what we’ve been seeing. It’s the primary decline since Might of 2023. And it’s actually notable as a result of costs have risen just about each single month going again 13 years. There was a handful of months in 2023 when charges have been going up and folks have been sort of pausing to see what was happening.
However actually for 13 years, this streak has continued. And if you happen to take a look at how quickly issues are altering, that’s why I feel we could be in a sustained decline as a result of simply two months in the past in August, costs have been up two and a half p.c yr over yr. So that’s notable. However in fact we even have to acknowledge a 0.4% decline, you’re most likely questioning, does that actually matter that a lot? Actually, no. For one month, no, it doesn’t, but it surely’s the route of the market that issues greater than the magnitude of the decline proper now. And the truth that we have now seen this flip, I feel actually issues. Now we’re going to speak about what this implies, however I simply wish to name out that this isn’t a shock. When you’ve got been listening to the present, The Housing Market Replace, the stuff that I speak about right here on our sister podcast in the marketplace on a regular basis, I’ve been saying that dwelling costs have been going to show unfavourable.
I do a prediction yearly on the present, and I mentioned final November that my vary for nationwide dwelling costs in 2026 was going to be between unfavourable 4% and plus 2%. So if you happen to common that out, my guess was at the moment this yr, we’d be someplace round unfavourable 1% and Redfin now has us at unfavourable 0.4% for October. I feel November will probably be actually darn near that unfavourable 1% I predicted. So not making an attempt to take a victory lap, I’m simply saying that that is precisely if you happen to research the market, what you ought to be anticipating. It’s been brewing for years now. Affordability within the housing market must get higher for the market to enhance. And we get that both from mortgage charges, which we’re going to speak about, wage progress, like are individuals getting paid extra? The reply isn’t any. Wage progress in actual phrases, inflation adjusted phrases is unfavourable proper now or costs happening, which is precisely what we’re seeing proper now.
So not a shock, however we should always speak about how the market is declining. So let’s break down what’s happening behind the scenes. Demand is the actual story and that’s the massive change as a result of anytime you see a market decline, costs go up or down, proper? It’s at all times a perform of provide and demand. And demand proper now to me is the large story. It’s the large factor that has modified over the previous few months. Pending gross sales, which is a good measure of demand. It’s mainly how many individuals exit and signal contracts to buy a house, fell 3.6% month over month, which is loads, contemplating that they’re already down 15% yr over yr. And we’re already on the lowest stage since 2013. So apart from that blip in April 2020 rest room paper weekend when nobody was doing something, I don’t really matter that.
In the event you take a look at all comparatively regular months within the housing market, lowest it’s been in a really, very very long time. Briefly, individuals aren’t shopping for houses. And also you would possibly say, certain, that’s been occurring for years. Form of true. Certain. We’ve had abnormally low demand for some time. We measure this by complete dwelling purchases in a yr. That’s about 4 million since charges began going up. Regular is like 5 and 1 / 4 million. However seeing it go even beneath that’s uncommon as a result of that 4 million stage has been fairly steady. From 2022 to 2 months in the past, it’s been fairly constant. So are there much less transaction? Is there much less demand? Sure. However was it in a free fall? Completely not. It’s been extremely steady. Now it’s falling. Actually, closed gross sales, the truly accomplished purchases fell their lowest stage since 2023. We had been at current dwelling gross sales operating at about 4.1 million.
I simply noticed a quantity right this moment that mentioned we’re at about 3.75 million. That may be a large decline. And the reasoning for that is apparent, proper? It’s easy. Mortgage charges averaged nearly 7.4% in October, in line with Redfin, which is a three-year excessive. In the event you take a look at the place they have been simply in September, they have been at 6.9%. In the event you take a look at the place they have been initially of the yr, they have been shut to six%. And there’s each an actual mathematical and a psychological obstacle to demand if you hit 7%. Folks need a 6% in entrance of their mortgage. They’re not going to purchase as a lot. And we’re seeing that mirrored within the knowledge. As Chen Zhao, who’s been a visitor on the present earlier than, she is the pinnacle of economics at Redfin. She put it this manner, and I feel it completely sums it up. She mentioned, “It’s a purchaser’s market, however not many individuals can afford to purchase.” That’s actually the entire market in a single sentence, and I feel the chance for traders.
As a result of if you concentrate on that, and we’ll speak about this extra later, if you concentrate on it, it’s a purchaser’s market. You may have the leverage as a purchaser, however you don’t have a number of competitors. Not lots of people are shopping for. That’s the place alternative exists. However once more, demand is the story of what’s altering. Let’s discuss concerning the provide facet although, as a result of that actually issues about the place this goes from right here. As a result of though there’s much less demand, we are literally seeing an vital nuance within the knowledge that actually individuals don’t like to speak about as a result of it’s not as sensationalist, it doesn’t get as many clicks, however there are fewer sellers proper now. Fewer individuals are truly selecting to promote their dwelling. New listings, which is the measure of people that put their dwelling up on the market for the primary time, fell month over month. It’s down 4% yr over yr and it’s down 1% month over month.
Now, these aren’t large declines, however what it tells us is that sellers are reacting rationally and the way you’ll count on in this sort of market. Much less individuals are shopping for houses, I’m not going to promote my dwelling. That’s how they’re reacting to it. In order that tells us, is the underside falling out of the market? Not proper now. At the very least there’s not panic promoting current. That mentioned, stock will go up. I made this prediction over the summer time when it was clear the struggle in Iran wasn’t ending anytime quickly, that we’d see costs go down, we’d see new listings go down, however we’d see energetic stock go up. All these issues have turned out to be true. Energetic listings are up now 1% from September and the very best since early 2020. Now, if you happen to’re questioning how does this occur? How do you get decrease new listings and better stock?
It’s easy. Principally, the properties that do get listed aren’t promoting rapidly. They’re sitting in the marketplace longer. Stock isn’t rising as a result of sellers are flooding the market. It isn’t rising due to misery. It’s rising as a result of houses aren’t promoting. Stuff is sitting. And this issues as a result of a crash, nearly all cases of a crash want compelled promoting. You might want to have individuals flooding the market with increasingly stock, and that’s not it. We’ve got reluctant sellers. When demand drops, lots of people who would think about promoting simply don’t. They only don’t promote. That’s self-correcting mechanism out there that reveals us, sure, we’re in a correction as I’ve been speaking about for years, however are we in a crash? I don’t assume so. The information doesn’t recommend that. In order an investor, like I mentioned, it creates alternative, proper? Stuff sitting in the marketplace longer.
We’re in a purchaser’s market, which is a good time to make use of your leverage, however the backside isn’t falling out proper now. And we’ll speak about a number of the different sources of compelled promoting like foreclosures and delinquencies in direction of the top of the present in our danger report. However let’s simply speak about this as a chance proper now as a result of purchaser leverage is tremendous excessive proper now. Let me simply learn to you a few stats that show this. The share of houses which can be promoting beneath listing value are actually 61%. So the vast majority of houses not promoting for listing value. The variety of houses which have a value lower, highest in Redfin’s historical past at 36%. Pending gross sales that fell out of contract, this actually spooks sellers. This is among the issues that creates leverage. The perfect leverage is that they get it beneath contract after which it will get canceled.
That provides you a number of leverage, 15%. And the common sale to listing ratio, which is mainly they listing it for $100,000, what does it promote for? On common, $96,000. 4% off listing value is the common on a typical deal. So these are the alternatives that traders ought to be seeing proper now. You bought to watch out, you bought to purchase beneath market comps, however the leverage is right here for the primary time, I don’t even know, since 2015 presumably. It’s been a extremely very long time since we’ve had this a lot leverage as patrons. Now in fact, and I say this each time and simply know that that is at all times true that actual property is regional. I’m speaking concerning the nationwide market, however in some markets it’s simply full on purchaser’s market. I dwell in Seattle. Costs are down 5% yr over yr right here. I can inform you proper now it’s a purchaser’s marketplace for certain.
Austin continues to get completely destroyed. It’s been down for years and it’s down one other six and a half p.c this yr. Nashville, a earlier darling of the pandemic growth, down 5%. So remember the fact that what I’m speaking about is a nationwide foundation. You really want to know your market. In the event you’re in a market like Seattle the place issues are sitting longer, stock goes up, you bought a number of choices. Be affected person, but additionally be aggressive. I do know this sound like type of contradictory issues, however be aggressive in making provides and searching for offers. Be affected person and wait to really execute on one thing till you discover a slamming deal as a result of you could find it if you happen to’re affected person, however be energetic out there. In the event you’re in a market like San Francisco, you’re going to need to deal with it in a different way. Or if you happen to’re in areas in New Jersey or Pittsburgh, you’re going to need to deal with it in a different way.
So just be sure you are learning your individual market info earlier than you go on the market and make provides. You’ll find a number of this info free of charge on Zillow or Redfin or no matter. In order that’s what’s happening out there. And if you wish to know what’s coming subsequent, we acquired to type of begin taking a look at what’s occurring behind the scenes when it comes to danger and affordability. If costs are softening, might we get a charge lower that comes right down to bail everybody out? To reply that, we acquired to speak about inflation and the Fed as a result of the CBI report we acquired the opposite day doesn’t assist. We’re going to get to that proper after this fast break. Keep on with us.
Welcome again to the BiggerPockets Podcast. I’m Dave Meyer. We’re doing our November 2026 housing market replace. We talked concerning the market earlier than. Now let’s flip our consideration to the large information that is happening with the Fed and mortgage charges. We simply acquired knowledge in November for October about inflation and it wasn’t good. It was a reasonably ugly report. The headline CPI’s Shopper Value Index, it’s essentially the most notable manner we measure inflation in the USA. It went up 0.4% in October alone. In order that’s only one month. In the event you extrapolate that out, which means annualized, that will be shut to five%. It’d be 4.8%. And that’s after a 0.6% leap in September. So simply the final two months, costs went up 1%. That may be a lot. That’s not good for the financial system. That’s the headline CPI. However I feel maybe much more regarding was that the core CPI, which excludes vitality prices like gasoline, which is a big driver of inflation proper now, and meals, one other massive driver of inflation proper now, if you happen to take these issues out of it, inflation nonetheless went up 0.3%.
That’s three months in a row at 0.3%. Meaning even with out all this unstable stuff and oil costs and all that, within the final three months, core CPI went up nearly 1%. In order that signifies that inflation is spreading to different components of the financial system. It’s not simply vitality. We’re seeing that vitality, as a result of it’s so a lot part of every little thing within the financial system, it’s bleeding into meals, to not point out that a number of fertilizer goes via strait of Hormuz. So we’re seeing fertilizer costs go up, that interprets into greater meals costs. We’re seeing the price of providers go up, which isn’t nice as a result of service inflation is extremely sticky and nearly by no means comes again down. And mainly every little thing else has gone up. It’s one thing that I mentioned would occur again in February. Really, I’ve been speaking about this for 2 years. Tariffs are inflationary.
We’re seeing that within the financial system. The struggle in Iran has created a number of inflationary and strain as effectively. And so this can be a downside. That is one thing that isn’t going to go away in a single day. We get inflation studies in arrear wanting backwards, however truly the Cleveland Federal Reserve has this factor referred to as the Nowcast the place they forecast inflation in actual time. They’re taking a look at nearly 4% yr over yr, so truly getting worse than it’s proper now. This sucks. I’ll simply be sincere. It’s horrible for everybody. It’s turned actual wage progress unfavourable. Spending energy for the common American goes down. It hurts all of us daily as we exit and purchase issues. That’s all true. However as a result of this can be a actual property present, let’s speak about what this implies for mortgage charges. Firstly, the Fed goes to lift charges.
It’s going to occur. It’s only a query of when and the way a lot. I don’t know if it’s on the subsequent assembly. I don’t know if it’s 25 foundation factors or 50, however I’m simply going to inform you proper now, the Fed goes to lift charges. That is very clear. The roles market is outperforming. Inflation is worse than anticipated. It is a basic state of affairs the place they’re going to lift charges, it’s going to occur. So if you’re within the charge cuts are coming in 2026 camp, we’re all going to be saved. I’m sorry. We’re not even debating when the Fed cuts anymore. We’re debating what number of occasions and the way often it occurs from right here. And once more, identical to the housing market happening and seeing costs happening, this isn’t a shock. I’ve been speaking about this for some time, that inflation is worse than individuals assume.
I mentioned this a yr and a half in the past that I feel it was going to come back again and we’re seeing that proper now. I used to be predicting that based mostly on tariffs. Nobody actually noticed the struggle in Iran coming, however that has additionally pushed up inflation as effectively. So the speed cuts aren’t going to occur. And that does matter for the housing market. It issues for industrial actual property as a result of these mortgages are way more tied to short-term lending charges. It’s going to matter for individuals who have HELOCs and that sort of stuff, but it surely doesn’t actually matter for 30-year mounted charge mortgages. For the residential market, we care about bond charges. And so what occurs with the Fed, not as vital, however what occurs with inflation is tremendous vital. Mortgage charges within the US are set largely by what’s happening with the bond market, particularly the 10-year US Treasury, and bond traders are tremendous delicate to inflation.
When inflation goes excessive, bond yields go up, that takes mortgage charges up with them. And we’re simply seeing this proper now. Simply in September alone, the 10-year treasury spiked 53 foundation factors. That may be a lot. Only for context, it’s usually about 4.2, 4.3, 0.5 during the last couple of years. It hit 5.3 in October. And I do know that may not sound like an enormous distinction. I promise you it’s vastly consequential as a result of which means if we went from 4.3 to five.3 within the final yr, that’s the entire cause mortgage charges have gone up. Now they’ve come again down just a little bit, however they’re nonetheless above 5% as of right this moment, and we’re seeing mortgage charges within the low sevens accordingly. And so I encourage you to do not forget that it’s not what goes on with the Fed. It’s what occurs with inflation. And if we wish mortgage charges to go down, we want inflation to go down.
That’s completely the way it works. And I’m going to say one thing just a little contradictory right here, however I feel it’s true that due to that truth and the way unsuitable lots of people get this and discuss concerning the Fed fully unsuitable, I truly assume a Fed charge hike could be one of many higher issues that we will do for mortgage charges. In the event that they lowered charges proper now, what wouldn’t it say to the bond market? It will inform them that they aren’t critical about inflation and that will freak out bond traders and yields would go up. Mortgage charges would go up in the event that they lowered charges proper now. I do know that sounds loopy, but it surely’s true. I mentioned this a yr in the past after they have been slicing charges. I mentioned, “I wager you in the event that they lower charges, mortgage charges go up.” And that’s what occurred. We noticed that.
Though they have been slicing charges final yr, sure, charges went down just a little bit, however proper after the cuts, mortgage charges went up. And I feel it’s as a result of bond traders care a lot about inflation, they wish to see the Fed is critical about combating inflation, which they do by elevating rates of interest. So is it going to repair mortgage charges within the quick time period? No. However when you have a bond market that believes that the Fed is taking inflation significantly and so they’re going to do what they will to battle inflation over the long term, that’s one of the best ways for us to get sustained decrease mortgage charges. So I personally help a Fed charge. I feel it makes a number of sense. Inflation, I don’t have time to get into it right this moment. It crushes an financial system. It’s so dangerous for an financial system. The Fed has to take this significantly, and I’m glad to see that they’re.
So that is good for the long-term well being of the housing market. It’s not going to repair something within the quick time period, however I simply wish to name out as I often do, don’t rely on mortgage charges coming down. Though every little thing I simply mentioned that I feel it’s a great coverage for them to lift the federal funds charge as a result of I feel that can assist in the long term, underwrite your offers with mortgage charges as they’re right this moment. In the event you’re going to get an arm, get a protracted one. I feel arms are going up in recognition. They’ll have their time in place. They’ll work for some forms of offers. I’m not at all times in opposition to arms, however if you happen to’re shopping for an asset that you simply wish to maintain for 30 years, don’t get an arm as a result of who is aware of? Charges might go up, proper? We’ve seen mortgage charges manner greater than they’re right this moment.
I’m not saying they’ll essentially go that manner. I’m inspired by what the Fed is doing proper now, however don’t rely on it. So plan on charges close to 7%, and this isn’t as a result of I’m making an attempt to be pessimistic. I’m making an attempt to be real looking. Inflation is sizzling proper now. The Fed is mountain climbing. Even when that works, it’s going to take some time. Frankly, the Fed elevating charges might be not sufficient. We want most likely the struggle in Iran and oil costs to come back down for this to considerably change within the quick time period. I feel any pullback on tariffs would most likely assist, however that can nonetheless take months for these issues to be mirrored. So plan on greater charges. And if they arrive down, nice. It’s a bonus, however simply underwrite like they received’t. And due to this actuality, I don’t like being the bearer of this information, however due to this actuality, it’s why I feel costs are going to proceed to go down as a result of bear in mind I mentioned affordability has to enhance out there and there are three ways in which occurs, actual wages, mortgage charges, costs.
Actual wages and mortgage charges are shifting within the unsuitable route, which suggests the adjustment has to come back in value. However let’s speak about how massive of a value correction might occur as a result of clearly there’s an enormous spectrum and distinction between a 2% drop and a 20% drop in the way you make investments. So we’re going to get to that proper after this break. Keep on with us.
Welcome again to the BiggerPockets Podcast. I’m Dave Meyer. Immediately is our November housing market replace. We’ve talked concerning the market. We’ve talked about mortgage charges. Now let’s speak about danger as a result of as I mentioned proper earlier than the break, I feel costs are going to come back down. I although that this yr, that’s in the end what wound up occurring. And I feel this pattern goes to proceed. Costs are softening, gross sales are falling, charges are caught, the Fed is mountain climbing. That mixture is precisely what you count on for a correction. It’s additionally a mixture that makes you look and say, how a lot danger is out there proper now? Is it a great time to speculate? So let’s leap into that. First, the excellent news. In the event you take a look at the well being of the housing market normally and the way a lot danger there’s, there’s a number of excellent news. The principle level is mortgage holders have a ton of fairness, essentially the most ever, by far $17.5 trillion in house owner fairness.
That’s wild. It’s up 1.4% yr over yr. There’s one other measure referred to as tappable fairness, which is mainly individuals can refinance or pull cash out of their dwelling and nonetheless keep 20% down. That market is very large. It’s $11 trillion. The typical house owner is tappable fairness of $204,000. That’s unbelievable. So if you happen to simply take a look at are individuals going to panic promote and wish to dump properties, the reply isn’t any, proper? Fairness wealthy house owners don’t actually do misery gross sales. They promote on their very own phrases or they don’t promote in any respect. That’s the core cause why when individuals examine what’s occurring proper now to 2008, it doesn’t actually match up. It’s one of many core causes I ought to say. There’s additionally loads about credit score high quality and all of this totally different stuff, the lock-in impact. That is one space the place there’s not danger in any respect, proper? The second factor we have to take a look at although is delinquencies as a result of frankly, misery is extra vital in my view in delinquencies as a result of even if you happen to’re underwater in your mortgage, you don’t get foreclosed on.
You simply don’t. You solely get foreclosed on if you happen to cease paying your mortgage, and that’s why we take a look at delinquencies. So delinquencies are rising, however they’re nonetheless fairly regular. They’re in a standard band that we’d count on to see. The nationwide delinquency charge is 3.66%. That’s up just a little bit month over month, which usually occurs this time of yr. There’s seasonality to this as effectively, but it surely’s up 24 foundation factors yr over yr. That’s notable, however nonetheless beneath each pre-pandemic September that we have now on report. So not one thing that’s actually regarding proper now, however we acquired to dig into the info as a result of there’s some nuance to this. In the event you break down the info of various kinds of mortgages, there’s some misery. It’s not in standard mortgages, the GSEs, Fannie Mae, Freddie Mac, very low ranges of misery there. FHA loans actually spiked loads.
In 2025 and the start of this yr, we noticed FHA mortgage delinquency go from like 4 or 5% nearer to six%. Doesn’t sound like loads, however that does matter. However the excellent news is during the last couple of months, it’s truly declined and leveled down. It’s nonetheless nearer to six% than it was a yr in the past. So I’m not saying it’s gotten all higher, that downside isn’t solved, but it surely’s not like a runaway practice, proper? It’s not simply getting worse each single month, which once more, if we have been seeing or skilled the start of a crash, we’d most likely see this going up quickly or not. It’s truly flattened and declined just a little bit during the last couple of months. Now, if you happen to take a look at VA loans, veterans loans, that’s going up as effectively. And in order that one hasn’t leveled off. It’s nonetheless near that 4% stage, however remember the fact that FHA and VA loans is lower than 1 / 4 of the market.
So though there’s misery, we’re speaking about 5% misery on 23% of the market, proper? It’s lower than 5% of the overall market that’s experiencing some misery. I’m not writing that off. That’s extra stress out there than we have now seen in a very long time, however it is usually nonetheless higher than the place we have been in 2019 and it’s not even in the identical sentence as the place we have been in 2009, 2010, something like that. So in my view, total stress out there stays fairly low. That mentioned, we’re going to see foreclosures numbers proceed to tick up as a result of misery occurred a yr in the past and it takes a yr or two to get to the foreclosures stage, proper? Individuals are delinquent, then they’re critical delinquent, then they’re pre-foreclosure, then they’re energetic foreclosures, then they’re foreclosures gross sales. That’s the pipeline. And individuals are working their manner via that sadly, however the variety of individuals going into the start of that funnel, it’s happening.
So we’re not in any type of emergency. Preserve that in thoughts as you hear this knowledge about foreclosures numbers going up. It’s true, but it surely’s effectively inside a standard vary. We’re at an artificially low vary for some time. Now it’s considerably regular. So foreclosures have normalized off historic lows. It’s not some wave. In the event you’re ready for some flood of bank-owned offers, you’re going to be ready some time. Now, the opposite space of misery that I wish to name out is there are actually 1.1 million underwater debtors. That is 2% of mortgage holders. Principally, if you happen to bought your own home, you’d need to carry money to the closing desk to get out of your mortgage. That’s fairly critical. One other three and a half million sellers have lower than 10% fairness. So if you happen to consider commissions, they could have to carry money to the closing desk too.
2% of mortgage holders being underwater isn’t nice. However once more, these individuals are not compelled to promote. They don’t need to do something in the event that they’re making their mortgage funds. However this underwater is extremely concentrated in two methods. First, it’s concentrated in FHA and VA loans, like we have been speaking about. This tends to be people on the decrease finish of the credit score spectrum, and so we’re seeing delinquencies go up there. And since you put much less down, the Likelihood that you’ve unfavourable fairness is up. In the event you solely put three and a half p.c down, your market goes down 4%, you’re underwater. In the event you put 20% down and your market goes down 3%, you’re not underwater. So it is smart that these low down fee packages have a better charge of being underwater. The opposite factor it is best to know is it’s extremely regional. Virtually the huge, huge, overwhelming majority of those underwater mortgages are going down within the American South.
So locations like Austin, Texas, San Antonio, all throughout Florida, in Phoenix, some locations in Colorado, we’re beginning to see it as effectively. And I feel it’ll proceed, however once more, it’s not widespread. All this to say, I feel the danger out there isn’t within the present knowledge. In the event you take a look at the place knowledge is right this moment, there actually simply isn’t that a lot danger on a historic perspective. So if we proceed on this trajectory, I feel, yeah, we’ll most likely see very modest value declines subsequent yr. Low single digits. I don’t know precisely, however off the highest of my head, say unfavourable two, unfavourable 5%, someplace in there most likely on a nationwide foundation. Regular correction. The place the danger lies, in my view, comes right down to the labor market as a result of if we see these AI fears truly come true and we see seven, 8% unemployment, we’re going to see extra misery out there, 100% that can occur, but it surely simply hasn’t manifest but.
The labor market is holding up higher than I feel anybody, not less than actually higher than I believed it might. And if that continues, we’re simply within the nice stall. It simply continues. If we see unemployment go up, there’s an attention-grabbing factor that can occur. So will we see extra misery? Sure, we’ll. Nevertheless it’s most likely the perform of a recession or a inventory market crash or a mixture of the 2. And if that occurs, sure, we could have extra misery, however that’s the different factor apart from beating inflation that would carry down mortgage charges. So we’ll get extra misery, however we’ll most likely get extra patrons. And that is the explanation I feel the danger of a full scale crash stays low even when the labor market will get a bit worse. Now, if we’re speaking 10 plus p.c unemployment, some individuals at AI speaking about 20% unemployment, that’s fully unprecedented within the historical past of the USA, going again mainly to the nice despair.
It hasn’t occurred in 100 years. If that occurs, yeah, there’s going to be some issues within the housing marketplace for certain, however there’s no proof. There’s a number of hypothesis that may occur. It’s not occurring proper now. So if you happen to’re apprehensive about danger out there, that’s the place I’d pay essentially the most consideration. In order that’s what we acquired for our present right this moment. Let’s simply recap right here and put collectively all of the items. Costs flip unfavourable nationally. That is true. Demand is at a 13-year low. Stock at a six-year excessive. Inflation’s actually accelerating. The Fed is mountain climbing and danger is there in some components of the market, however that is additionally a chance, proper? If you’re a purchase and maintain proprietor, don’t panic. Don’t go promote issues since you simply noticed that costs are happening. It’s a paper loss. You may have mounted charge debt, you bought reserves, it’s cashflowing, you don’t have to promote issues.
You possibly can if you happen to see higher alternatives on the market, however you don’t have to. So take a breath there. The second factor is patrons with dry powder, that is your market. Not as a result of costs are low-cost but, as a result of leverage has shifted to you and there aren’t a number of patrons. If you’re a purchaser proper now, you’re going to have an incredible quantity of negotiating leverage. So completely use it. Third factor to recollect, tough marketplace for flippers. In the event you’re holding onto one thing for a brief time frame, that is an extremely tough market to be in, so simply be actually cautious. Flippers can spend money on a correction. It’s the transition from a vendor’s market to a purchaser’s market that hits flippers and we’re in that transition. We haven’t hit the total transition but, so there are a number of flippers caught in between. So simply watch out as we undergo this transition.
As soon as costs go down and you may purchase at a greater value, then issues are okay once more, however we’re nonetheless in that bizarre transitionary stage, so it’s a time to be additional cautious. That’s our present for right this moment, everybody. Thanks a lot for watching this episode of our housing market replace. I’m Dave Meyer for BiggerPockets, and I’ll see you all quickly.
Assist us attain new listeners on iTunes by leaving us a ranking and evaluate! It takes simply 30 seconds and directions could be discovered right here. Thanks! We actually recognize it!
Curious about studying extra about right this moment’s sponsors or changing into a BiggerPockets accomplice your self? Electronic mail [email protected].