
Business gamers are contemplating the unthinkable
Disaster and flood
Written by Daniel Wooden
Because the insurance coverage {industry} experiences vital losses, some {industry} gamers are questioning the unthinkable: “Will the insurance coverage {industry} collapse?” Australia’s regulators and insurance coverage leaders had been requested this query throughout a authorities inquiry listening to.
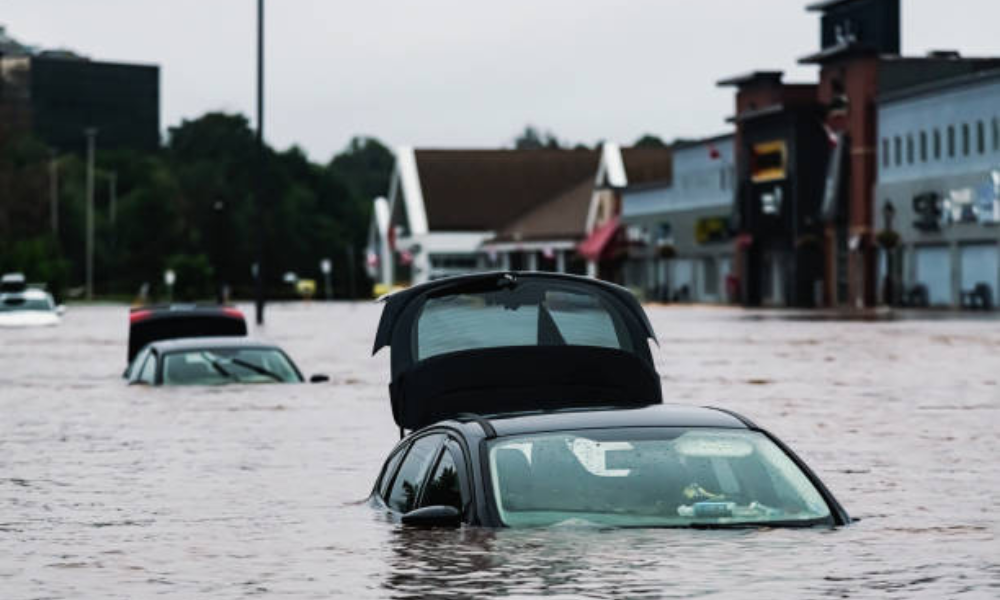
The examine appears on the insolvency and unavailability of insurance coverage claims on account of local weather change disasters, such because the 2022 floods which price the {industry} a nationwide document A$6.3 billion in losses.
Because the listening to was underway, the state of Florida was hit by the primary of a collection of hurricanes in the USA. In response to estimates, the overall insurance coverage premiums for hurricanes Helen and Milton might attain US$55 billion.
In late September, heavy rains occurred in Nepal, inflicting flooding and landslides. The United Nations reported that greater than 200 individuals had been killed and 4,500 individuals had been rescued. Capital Kathmandu flooded. Nevertheless, insured losses had been comparatively low.
In the meantime, Canada skilled its most harmful summer time on document, with losses of C$7 billion on account of floods and wildfires. Flooding is presently occurring within the UK, significantly in Wales. There was an unusually excessive quantity of precipitation in September, so 2023 was the wettest year in the country’s history.
On this context, it doesn’t appear far-fetched to query the survival of the insurance coverage {industry}.
She advised Christopher Wallace, CEO of the Australian Reinsurance Pool Company (ARPC), that if the collapse had been to happen, state-backed insurers like ARPC and reinsurers would “Will that be the one one left?” he mentioned.
Mr Wallace mentioned he had realized from conversations with authorities and the insurance coverage {industry} that there was “vital momentum” round “widespread excited about the right way to scale back catastrophe danger in our communities”.
“The long-term resolution is to cut back danger, not simply tackle insurance coverage premiums,” Wallace mentioned.
Insurance coverage corporations can “withdraw from the market”
The following {industry} member to face questions was Elaine Grace, CEO of the Society of Actuaries.
“Is there an actual danger that the insurance coverage {industry} will collapse if the local weather disaster continues, particularly with out dramatic reductions in emissions?” the Chair requested.
“The insurance coverage {industry} provides one yr of protection,” Grace says. “In that sense, they’re simply uncovered and may stroll out of the market at any time.”
Nevertheless, the CEO was involved that this meant that coping with local weather disasters would turn into the accountability of governments. Like Mr Wallace, she mentioned it was vital for governments, insurance coverage corporations and communities to work collectively to cut back danger.
Main insurance coverage {industry} physique says {industry} is sustainable ‘for now’
“If emissions do not fall and governments do not intervene, what’s the most dire state of affairs dealing with the insurance coverage {industry}?” Faruqui, in flip, requested Insurance coverage Council of Australia (ICA) chief working officer Kiley – requested Mr. MacFarlane.
“The very first thing I would wish to say is that the insurance coverage {industry} could be very aggressive and sustainable for the time being,” MacFarlane mentioned. “It is there to create a security web for Australians to take care of disasters that occur each day.”
Nevertheless, since Australia’s Black Summer season bushfires in 2019-2020, the insurance coverage {industry} has paid out greater than A$20 billion in excessive climate claims, he mentioned.
Insurtechs say parametrics may very well be the reply
Faruqui requested once more.
“Given our greenhouse gasoline emissions technique, is the very survival of the insurance coverage {industry} underneath severe risk except issues change?” she mentioned.
This time, Jonathan Barratt, CEO of insurtech firm CeliusPro Australia, answered. He mentioned “indemnity” insurance coverage was dealing with issues.
“I believe parametric options ought to be inspired as a result of they provide another methodology of danger switch,” Barratt mentioned.
He mentioned extra reinsurers and insurance coverage corporations are getting concerned in parametrics.
system stress
“Do you agree that there’s a actual danger that the insurance coverage {industry} itself will decline?” Faruqui requested once more, this time to a tutorial at Monash College in Melbourne.
“I believe there’s clearly a whole lot of stress on the system and personal insurers,” Dr. Antonia Settle mentioned. “There’s in all probability just a little bit extra nuance as as to if insurance coverage corporations will go bankrupt or not, and whether or not insurance coverage corporations will go bankrupt.”
Resolve lectures on family funds and monetary dangers.
“I believe the issue is extra that the market is shrinking and we’re turning into extra depending on state subsidies,” she says.
“The market is failing”
The listening to not solely thought-about the prospect of an industry-wide collapse, but in addition the affect of what many see as a partial collapse.
In California, insurance coverage corporations are fully withdrawing from the house insurance coverage market on account of hearth dangers. Australia has related protection challenges for flood, hearth and cyclone dangers, with a rising variety of areas the place insurance coverage is unavailable or unaffordable.
Tyrone Shandiman, chairman of the Australian Client Insurance coverage Foyer (ACIL) and managing director of insurance coverage intermediaries, mentioned “the market is failing” and known as for additional authorities intervention.
He was requested by the deputy chair of the inquiry, Labor senator Tony Sheldon, to spotlight why he thinks the well being sector is failing.
“I spoke to a pensioner in Townsville who needed to promote her unit as a result of she was charged $16,000 in premiums, 40% of her pension,” Shandy mentioned. Mr. Mann mentioned. “Why is not {that a} market failure?”
He mentioned ACIL has information displaying that some customers pay as much as 20 occasions extra in premiums than others. Shandiman mentioned many individuals residing in high-risk areas presently select to not insure in opposition to these dangers, requiring authorities help.
The rising “local weather change ghetto”
Karl Maron mentioned this rising drawback is probably going making a “local weather ghetto” in developed international locations.
Mallon is CEO of the Sydney-based Local weather Threat Group.
“In probably the most excessive conditions, we might want to purchase again the property, which suggests we should take the property off the market,” he mentioned. “They’re unsafe and never economically viable, so property rights ought to be withdrawn and reassigned to safer areas.”
He talked about New Zealand, the place property buybacks had been launched after extreme flooding.
Do you assume the insurance coverage {industry} will collapse? Share your ideas under.
Associated articles
Take a look at the most recent information and occasions
Be part of our mailing listing, it is free!